Samsung Wallet (Samsung Pay)

Screenshots
Details
- Rating
- 204.56K reviews
- Version
- 2.5.76
- Developer
- Samsung Electronics Co., Ltd.
Analysis by Norviv
I use my phone for far more than messages and photos, so a wallet app has to do more than place payment cards in one corner of the screen. Samsung Wallet is Samsung Electronics Co., Ltd.’s lifestyle app for keeping essential cards and related items on a compatible phone. In everyday use, its biggest appeal is reducing the number of physical cards I need to carry, while its biggest weakness is that the experience depends heavily on the phone, account setup, supported services, and the way I personally interact with a screen.
The app is free and intended for everyone, which makes it easy to try without adding another subscription to a monthly budget. It has been available since October 17, 2015, and its current version is 2.5.76. With an average rating of 4.1 from around 1.1 million ratings and over 100 million installs, it is clearly a familiar tool for a large Samsung audience. I would not treat popularity as proof that it suits every person, though. The useful question is whether its layout, payment flow, and dependence on a Samsung phone fit your own habits and abilities.
How Samsung Wallet feels to navigate and read
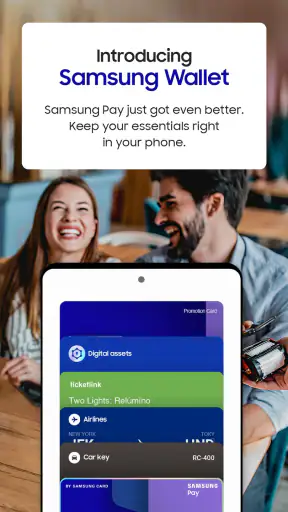
My first impression is that Samsung Wallet is built around quick recognition rather than deep browsing. Cards and other saved essentials are presented as items I can identify visually, which is more practical than searching through a long text-only list every time I need something. That design makes sense when I am standing at a checkout and want to reach the right card without thinking too much.
The main advantage for readability is the separation between the wallet’s contents and the rest of the phone. I do not have to open a banking app, find a payment section, and then work out which control starts a transaction. The wallet approach gives the task a clear purpose. For someone who already understands Samsung’s interface, the structure feels familiar enough that repeated use becomes less demanding.
There is still a learning curve. A new user may not immediately know which items are ready for payment, which are simply stored for reference, and which require another step before use. The visual card format is convenient, but it can also make similar-looking items harder to distinguish quickly. I recommend using clear, recognizable card names where the app allows it and removing old or duplicate entries instead of letting the wallet become a crowded digital drawer.
The most useful habit is to prepare the wallet before you are under pressure. I would add and organize cards at home, then test the opening and confirmation flow when I have time. That matters for people who read slowly, become distracted in busy places, or need extra time to interpret a screen. A few minutes of preparation can prevent a rushed search at a checkout.
The app’s language and visual hierarchy also matter for people with different reading needs. Large, distinct card imagery can be easier to scan than dense text, but visual recognition is not equally comfortable for everyone. Someone with low vision may prefer the phone’s existing display adjustments, text enlargement, or screen reader tools. Those system features can improve the experience, although the exact result will depend on the device and the person’s settings rather than on the wallet alone.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
Navigation that helps during a real purchase
Imagine I am buying groceries while holding a bag in one hand and trying not to block the line. The best wallet experience is one that lets me reach the intended card with a short, predictable sequence. Samsung Wallet is well suited to that kind of repeated routine once I have learned where my preferred card appears and how the payment confirmation works.
That predictability can be especially helpful for people who find multi-step banking apps tiring. A conventional banking application may expose balances, transfers, offers, security notices, and account tools before I reach the payment function. Samsung Wallet keeps the immediate wallet task more focused. On the other hand, a bank app is usually better when I need transaction details, account management, or a full explanation of what happened after a payment.
I would not rely on memory alone if several cards have similar colors or designs. A simple personal system helps: keep the card I use most often in the easiest position to recognize, and avoid storing items I no longer use. This is not a flashy feature, but it is one of the practical differences between a wallet that saves time and one that creates another search problem.
Motor, sensory, and cognitive considerations
For motor accessibility, a phone wallet can remove some physical obstacles. I do not have to pull several cards from a tight wallet, turn them over to find the right one, or hold a small plastic card at a particular angle. A digital card can be selected while the phone remains in my hand, which may be useful for people with limited dexterity or difficulty manipulating small objects.
That benefit has limits. A payment still involves holding a phone, tapping or swiping through controls, and completing whatever device security step is required. Someone with tremors, reduced reach, or difficulty making precise touches may find a large physical card easier than a phone screen. A phone case, wet fingers, gloves, or an awkward one-handed grip can add friction. I would test the complete action, not just the setup screens, before deciding that a digital wallet is automatically more accessible.
People with sensory sensitivities may appreciate not having to handle multiple cards or listen to a long verbal exchange while searching for one. The shorter routine can reduce stimulation in a busy shop. Yet checkout environments are unpredictable: bright lights, queues, background noise, and time pressure can make even a familiar interface harder to use. I find it helpful to open the wallet before reaching the payment terminal, when possible, rather than trying to perform every step after the cashier is waiting.
For screen-reader users, the important issue is whether the phone’s spoken navigation identifies cards, buttons, and status messages clearly enough. I would not assume that a visually simple card display automatically translates into an equally simple spoken experience. The sensible approach is to try the wallet with the accessibility tools already used on the phone and complete a low-pressure test before using it as the only payment method.
People with cognitive disabilities may benefit from a wallet that keeps payment cards together, but too many stored items can have the opposite effect. I prefer a deliberately small collection. Keeping only current cards reduces choices, lowers the chance of selecting the wrong one, and makes the interface easier to explain to a family member or support person. This is also useful for anyone who becomes overwhelmed by clutter.
Why the phone itself changes the experience
Samsung Wallet is not an independent object. It is part of a phone environment, so comfort with Samsung’s menus, screen settings, authentication behavior, and notifications affects the whole experience. A person who already uses a Samsung phone may find this integration more natural than switching between unrelated services. Someone using another brand, or someone who wants the same wallet experience across different phone ecosystems, should consider whether that dependence is acceptable.
Compared with carrying a physical wallet, the app can be lighter and easier to organize. Compared with a general mobile payment service, its strongest argument is the sense of being built into the Samsung experience. The trade-off is flexibility: a physical wallet works without a charged phone, and a cross-platform service may be more convenient for households using different brands. I would choose Samsung Wallet for a Samsung-centered routine, not simply because it is free.
One non-obvious advantage is that digital organization can make card rotation easier. If I use different cards for different purposes, I can keep them together instead of carrying every option. That can reduce bulk, but it also makes preparation more important. I need to know which card is selected before confirming a purchase, particularly when the cards have similar visual designs.
Using it in different situations and environments
At a quiet store, Samsung Wallet feels straightforward: I open it, identify the card, complete the phone’s requested confirmation, and present the device as instructed. At a crowded transit station or a noisy café, the same sequence demands more attention. I may not hear a spoken prompt, see a small status message clearly, or have enough space to hold the phone comfortably.
For that reason, I treat the app as a convenience rather than my only fallback. I keep a physical payment option available when I am traveling, going somewhere unfamiliar, or expecting poor access to charging. This is not a criticism unique to Samsung Wallet; it is the basic trade-off of replacing a physical object with a battery-powered phone. Still, it is an important consideration for older users, people with medical needs, and anyone who cannot easily troubleshoot a device in public.
Another practical scenario is helping someone else pay. A support worker, parent, or family member may be able to guide a user through a familiar phone routine more easily than through several different banking applications. The wallet can make the location of payment cards consistent. However, sharing a phone or handing it to another person introduces privacy and security concerns, so I would establish clear boundaries and use the phone’s normal protection features rather than treating the app as a shared communal wallet.
When traveling, I would also avoid assuming that a card saved in the app will behave exactly like a physical card in every location. Payment acceptance depends on the card, the terminal, the service involved, and local conditions. The app can simplify what I carry, but it cannot remove the need to understand my payment options. A backup card and a little preparation are more useful than discovering a limitation at the airport or hotel counter.
The app is also less helpful when my goal is financial oversight rather than quick access. If I want to compare spending, dispute a transaction, change account settings, or understand a bank’s detailed record, I would go to the relevant banking service. Samsung Wallet is best viewed as an access layer for essentials, not as a replacement for every financial tool on my phone.
Where the experience still creates barriers
The first barrier is ecosystem fit. The app makes the most sense for people already invested in Samsung’s phone environment. If my household uses several phone brands, or if I regularly move between devices, a broader wallet option may create less confusion. I also need to be comfortable keeping important payment access on a phone. That is a personal preference, but it affects whether the convenience feels reassuring or stressful.
The second barrier is recovery. A physical wallet is easy to understand when something goes wrong: I take out another card. With a phone wallet, I may need to deal with a locked device, an unclear confirmation state, a dead battery, or a card that is not accepted in a particular situation. Those problems may be rare in my normal routine, but inclusive design is not only about the ideal path. It is also about whether a person can recover without panic or outside help.
Visual card layouts can create ambiguity for users who cannot rely on color, shape, or small printed details. I would not recommend storing several nearly identical cards without a clear identification method. If the app or the phone offers naming, sorting, or other organization tools available in the current setup, I would use them. If not, the safest choice is to limit the number of active cards rather than depend on visual memory.
There is also a social barrier. Some people feel pressured when a payment takes longer than expected, and a digital wallet can make that pressure worse if the user is still learning the gestures or confirmation steps. A cashier may understand a physical card immediately but not know how to assist with a phone. Practicing the routine with a trusted person, or choosing less busy times for the first few attempts, can make adoption gentler.
Finally, “Everyone” as an age classification does not mean every user will experience the same ease of access. A child, an older adult, a person with low vision, and someone with limited hand movement may all need different settings and support. I see Samsung Wallet as potentially inclusive when paired with suitable phone adjustments and a simple card setup, but not as a complete accessibility solution by itself.
My inclusive verdict on Samsung Wallet
After using it as a practical phone wallet, I see Samsung Wallet as a strong choice for Samsung users who want fewer physical cards and a focused way to reach everyday essentials. Its free entry point, familiar card-based presentation, and large user base make it approachable. The app is particularly useful when I have a stable routine, know which card I need, and can use the phone comfortably with my preferred display and interaction settings.
I would recommend it to someone who finds a physical wallet difficult to organize, who benefits from keeping items in one predictable place, or who prefers a Samsung-centered setup. I would also suggest starting with one frequently used card, learning the full payment sequence, and keeping a backup option until the routine feels dependable. That approach exposes practical problems early without putting an important purchase at risk.
I would steer someone toward a physical wallet or a different mobile wallet if they need device independence, regularly switch between phone brands, cannot reliably keep a phone charged, or find touchscreen authentication more difficult than handling a card. A banking app remains the better companion for account management and detailed financial information. Samsung Wallet does not need to replace those alternatives to be useful.
My final view is positive but deliberately conditional: the app works best when its convenience is matched with a personal backup plan and thoughtful organization. It can make payment access quicker and reduce physical clutter, while its real accessibility depends on the phone, the user’s abilities, the surrounding environment, and the support available when something goes wrong. For the right Samsung user, that balance is worthwhile; for everyone else, the usual alternatives may be simpler and more dependable.
Frequently Asked Questions
01What is Samsung Wallet, and what can I use it for?
Samsung Wallet is Samsung’s mobile wallet and digital identity app, incorporating the features previously associated with Samsung Pay. After setting it up, you can add compatible credit, debit, prepaid, and membership cards, then use your phone or smartwatch for contactless payments at supported terminals. Depending on your country and device, it may also store boarding passes, loyalty cards, digital keys, tickets, coupons, and selected identification documents.
02Is Samsung Wallet safe for making payments and storing cards?
Samsung Wallet uses several security layers, including device authentication, tokenized payment details, Samsung Knox protection, and the ability to lock or erase wallet data remotely through Samsung’s account services. Merchants generally receive a transaction token rather than your actual card number. Even so, security also depends on using a strong screen lock, keeping your phone updated, avoiding suspicious software, and never sharing your PIN, fingerprint access, or account credentials.
03Which phones, cards, banks, and countries support Samsung Wallet?
Compatibility varies considerably by region, device model, Android version, bank, card network, and mobile carrier. Samsung Wallet is generally intended for supported Galaxy smartphones and some Galaxy watches, but not every model includes the same functions. Your bank or card issuer must also participate in the service. Before downloading or relying on it, check the official Samsung Wallet page and your local bank’s compatibility list, especially when traveling internationally.
04Can I use Samsung Wallet without an internet connection?
In many cases, Samsung Wallet can make contactless payments even when your phone is temporarily offline, because eligible payment credentials are securely stored for limited use. However, the number of offline transactions may be restricted, and the app needs an internet connection periodically to refresh security information. Other features, such as adding cards, synchronizing passes, updating account data, or downloading tickets, generally require connectivity and may not work offline.
05How do I set up Samsung Wallet, and what should I do if a payment fails?
Install or update Samsung Wallet on a compatible Galaxy device, sign in with your Samsung account, create or confirm a secure screen lock, and follow the instructions to add a supported card. You may need to verify the card through your bank by text message, email, or its banking application. If a payment fails, check NFC settings, confirm that the card is supported and active, unlock the phone before tapping, and contact the bank or merchant if the issue continues.


